
The Truth About Minimum Car Insurance Coverage: What is it and is it Enough?
When it comes to car insurance, every state has a baseline requirement — known as minimum car insurance coverage — that drivers must carry to legally get behind the wheel. These minimums vary by state but typically include liability coverage, which helps pay for damages and injuries you cause to someone else. Sounds simple, right?
 Minimum Car Insurance Coverage – The Insurance Stops
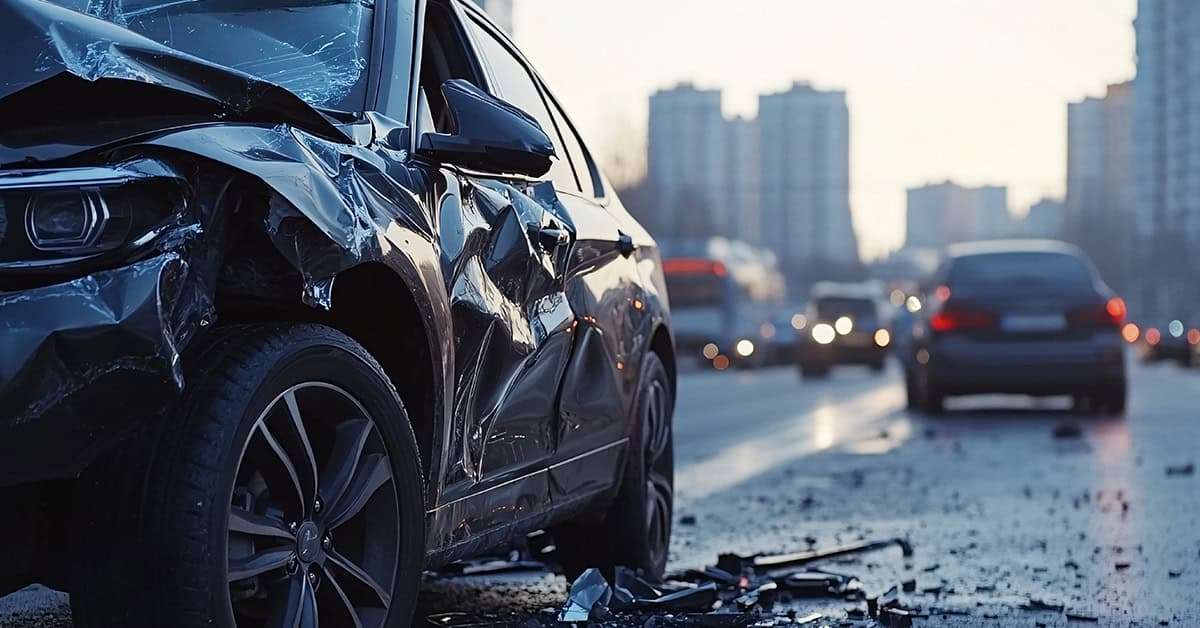
But here’s the catch: minimum car insurance coverage usually only protects other people — not you or your vehicle. That means if you get into an accident that’s your fault, you could be left paying out of pocket for your own medical expenses, car repairs, and more.
Let’s break it down further.
What Does Minimum Car Insurance Coverage Actually Cover?
Most states require drivers to carry two main types of liability insurance:
- Bodily Injury Liability (BIL): Covers medical expenses for the other driver and passengers if you’re at fault in an accident.
- Property Damage Liability (PDL): Pays for damages you cause to someone else’s vehicle or property.
That’s it. Minimum car insurance coverage typically does NOT cover:
- Repairs to your car after an accident.
- Medical bills for your injuries if you’re at fault.
- Damage caused by uninsured or underinsured drivers.
- Theft, vandalism, or weather-related damage.
So, if you rear-end someone at a stoplight, your policy will help pay for their car repairs — but not yours. And if your car gets stolen? You’re out of luck unless you have comprehensive coverage.
Why Minimum Car Insurance Coverage Might Not Be Enough
Let’s say you get into an accident in Colorado Springs, and you’re found at fault. Here’s a real-world scenario:
- The other driver’s medical bills total $40,000.
- Their car is totaled, worth $35,000.
- A passenger in their vehicle needs surgery, costing $50,000.
- With Colorado’s minimum car insurance coverage, your policy would only pay:
$25,000 toward the first driver’s medical bills (leaving you to cover the remaining $15,000).
$15,000 toward their vehicle replacement (leaving you responsible for the other $20,000).
$50,000 total for bodily injury per accident—but since the passenger alone had a $50,000 surgery, what about the driver’s medical bills?
Suddenly, you’re left paying tens of thousands of dollars out of pocket — all because state minimums weren’t enough.
How Much Coverage Do You Really Need?
Many experts recommend carrying at least 50/100/50 coverage — or even better, 100/300/100 — to ensure you’re better protected. Comprehensive and collision coverage can also help pay for your car repairs or replacements, as well as damages from theft or weather-related events.
The best part? Increasing your coverage doesn’t always mean doubling your premium. In many cases, adding extra protection only costs a few extra dollars a month — far less than what you’d pay out of pocket after a major accident.
Should You Stick With Minimum Car Insurance Coverage?
If you own an older car and don’t drive often, minimum coverage might be a reasonable choice. But for most drivers, it’s a risky gamble. Accidents happen when we least expect them, and one bad crash could leave you with a financial headache that lasts for years.
Before settling for the bare minimum, take a moment to evaluate:
- How much would it cost to replace your car out of pocket?
- Could you afford a lawsuit if damages exceed your coverage limits?
- Would extra protection give you greater peace of mind?
Protect Yourself with the Right Coverage
You don’t have to figure this out alone! The Insurance Stops can help you find the right balance between affordability and protection — ensuring you’re covered for whatever the road throws your way.
Don’t wait until it’s too late. Contact us today for a free quote and see how easy it is to upgrade your coverage without breaking the bank!


